Federal contracting 2026–2031:
A five-year outlook for contractors
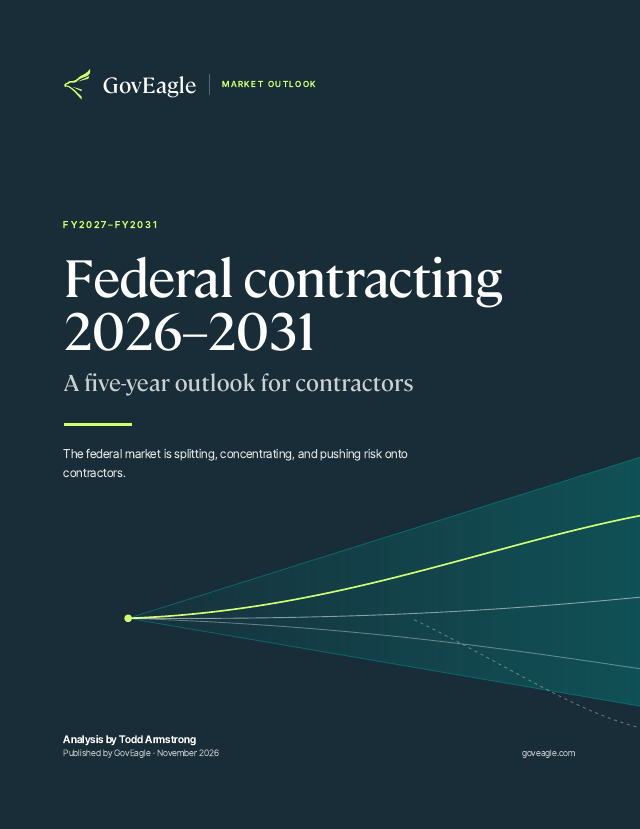
The federal market is splitting, concentrating, and pushing risk onto contractors. We rank seven findings, sketch four alternative futures for FY2031, and name the signposts that show which way things are heading.
Analysis by Todd Armstrong · Published by GovEagle · November 2026
FY2025 contract spending
Small businesses winning prime dollars
Seven shifts that will reshape the contractor market by FY2031
This report looks at how the federal contracting market is likely to change from FY2027 through FY2031 and what those changes mean for contractors. It uses strategic foresight methods: we look for the forces driving change, rate each one on how much it matters and how well the evidence supports it, and sketch the futures it could lead to. The result is seven ranked findings, four alternative futures for FY2031, and a list of signposts to watch. Wherever we could, we sourced the evidence to government records and company filings. The key above the findings explains our ratings, and How to read this report, near the end, defines every term we use.
The federal market is splitting, concentrating, and pushing risk onto contractors.
FY2025 contract obligations hit a record of about $793 billion, yet fewer firms shared them, civilian spending dipped, and the rules governing every phase of the buy are being rewritten at once.
Seven findings, ranked by impact × confidence
- Probability
- Almost certain (above 90%), likely (65–90%), plausible (35–65%) or possible (10–35%).
- Confidence (8/6/4/2)
- How well sources support a finding, from 8 (primary records, independently backed) to 2 (commercially interested or uncorroborated claims).
- Range
- Where the outcome sits in the cone of possibilities: probable, plausible or possible.
Two markets: defense surges while civilian contracting stalls
What it means: Cleared and engineering labor gets bid up as civilian-focused firms pivot toward defense.
Trend · Economic, Political (budget mix, reconciliation) · Rising (defense), flat-to-falling (civilian); accelerating split
Signposts: FY2027 appropriations and Reconciliation 3.0 outcome; civilian obligations in FY2026 data
Fewer small firms, while “small” is being redefined upward
What it means: If the size rule passes as drafted, set-aside competitions will fill with firms many times larger than today’s typical small business.
Trend + emerging issue · Legal, Political (SBA rule, set-aside law, 8(a) audit) · Falling vendor count; steady, possibly accelerating
Signposts: SBA size-standard final rule; FAR Part 19 proposed rule; FY2026 vendor counts
Risk moves to the contractor
What it means: Bidders price uncertainty in, so ill-defined work may draw fewer bids at higher prices.
Emerging issue (policy driver) · Political, Legal (executive orders, TINA statute, FAR changes) · Rising; accelerating since April 2026
Signposts: Share of obligations on fixed-price; renegotiation of agencies’ top-10 cost-type contracts; overrun disputes
Fewer, bigger doors
What it means: Many vehicles add new companies rarely or never, so missing the initial competition can mean a decade outside.
Trend · Political, Legal (OneGov, category management, protest rules) · Rising; steady
Signposts: OneGov expansion beyond software; protest thresholds; on-ramp frequency (OASIS+)
Neo-primes: the money is ahead of the market share
What it means: Expect near-term disappointment for defense startups (slow production orders, falling valuations) alongside a larger long-term role than today’s 1.3% share implies.
Hype gap over a real, slower trend · Economic, Technological, Legal (venture capital, OTAs, NDAA) · Rising from a tiny base; attention far outrunning adoption
Signposts: Nontraditional share of DoD obligations; production OTAs; first defense-tech IPOs
Rules in permanent motion
What it means: We expect this volatility to last through at least the 2028 election.
Stable condition (high volatility) · Legal, Political · Oscillating; no sign of settling
Signposts: CMMC task-force report; FAR final rules; CUI Rev 2 vs Rev 3 alignment
AI on both sides of the table
What it means: Differentiation may shift from prose quality to verifiable data: past-performance records, CPARS ratings and machine-checkable compliance.
Weak signal / emerging issue · Technological, Social (shrinking acquisition workforce) · Rising; early
Signposts: Agency AI evaluation policies; proposal-volume data; human-in-the-loop rules
Two markets: defense surges while civilian contracting stalls
Federal contracting is splitting into a fast-growing defense market and a flat or shrinking civilian one.
Indicator: obligations by department, the budget request mix, and contractors’ segment results.
FY2025 spending. GAO puts FY2025 contract obligations at about $793 billion, up $17.8 billion after inflation, with defense agencies at about $491 billion (62%) and civilian agencies at about $301 billion (GAO; GAO dashboard).
Inside civilian services, GAO’s largest professional-services category (“professional support: other”) fell from about $23 billion in FY2024 to $18 billion in FY2025, a drop of roughly a fifth, and lost the top spot to VA-driven managed healthcare ($23.6 billion). The advisory work many civilian contractors sell shrank, while VA health-care spending kept growing.
FY2027 budget. The request asks for $1.5 trillion for defense ($1.15 trillion in the regular budget plus $350 billion in reconciliation), while requesting a 10% cut ($73 billion) to non-defense discretionary spending (OMB FY2027 Budget, Tables S–2 and S–3; CSIS).
The defense request is high, but far from assured. Both the House and Senate budget resolutions allow just $60 billion for defense, and Senate action has slipped past the November election (CSIS; BGov).
In June the White House also requested $87.6 billion in supplemental funding, mostly for Operation Epic Fury, the war with Iran, including $67.1 billion for the Pentagon and $21 billion for munitions and the industrial base (OMB request, House Doc. 119-171). It has not been enacted, and Republicans have sought to fold its priorities into the stalled reconciliation bill (CSIS).
Company results confirm the defense growth and add detail on the civilian side.
- RTX’s missile and air-defense business booked $52.3 billion of defense orders in the third quarter of 2026, against $15.9 billion a year earlier, nearly doubling its backlog to $130 billion on multiyear Tomahawk and AMRAAM contracts (RTX).
- Defense and intelligence revenue also grew at Leidos (+8% in the quarter ended July 3, 2026) and SAIC (+5% in the quarter ended July 31, 2026).
The civilian decline is real but uneven.
- Booz Allen’s civil revenue fell about 23% in the quarter ended March 31, 2026, and its own investor presentation describes “market bifurcation… with continued growth in National Security; Civil still working through challenging comps” (Booz Allen results; presentation).
- Leidos’s non-defense federal revenue fell about 5% (mostly from a single VA program), while SAIC’s civilian segment grew 9% (Leidos; SAIC).
The squeeze lands hardest on advisory and consulting work, rather than on civilian IT across the board.
Direction and momentum. Defense rising and accelerating; civilian flat to falling.
Horizon. The full five years, with an uncertain slope. OMB’s budget plans reconciliation money only for 2027; after that, total defense drops to $1.28 trillion in 2028 before climbing to $1.35 trillion in 2031, while non-defense programs are cut 10% in 2027 and another 2% each year after, reaching $609 billion by 2031 (OMB FY2027 Budget, Table S–2).
Cleared and engineering labor gets bid up as civilian-focused firms pivot toward defense. Civilian advisory and consulting firms face recompetes that buy less (narrower scopes, fewer staff, lower ceilings). Firms whose past performance is purely civilian may find their credentials worth less in the growing half of the market.
Likely (65–90%) that defense keeps a larger share in FY2031 than in FY2024. Plausible (35–65%) that the gap narrows after 2028.
Plausible · 8. Corroborated across GAO data, OMB’s budget, Bloomberg Government analysis, and four contractors’ SEC filings.
Reconciliation 3.0 failing and a post-midterm Congress restoring civilian funding in full-year FY2027 bills.
Fewer small firms, while “small” is being redefined upward
The number of small businesses winning prime awards keeps falling, even as the definition of “small” is poised to expand sharply.
Indicator: count of small-business prime awardees; proposed SBA size thresholds.
Vendor counts. The number of small businesses receiving federal contract dollars fell from 93,707 in FY2014 to 60,951 in FY2024, a drop of more than a third (SBA Small Business Data Hub), and to 56,725 in FY2025 (Washington Technology).
Defense shows the same pattern: 43,621 small businesses in FY2014, down 32% to 29,584 in FY2024 (SBA Data Hub). On the civilian side, Bloomberg Government counted 51,632 small businesses in FY2025, down 4%, the 14th annual decline in 15 years (BGov).
New entrants have also dried up in the 8(a) program: a June 2026 report from Sen. Ed Markey found certification approvals down 92%, with none since August 2025, during SBA’s program-wide audit (FNN; SBA).
The size rule. SBA’s August 2026 proposed rule would rewrite who counts as a small business. It would replace nearly 1,000 industry size standards, the eligibility limits that decide which firms qualify as small, with 338, and remove today’s upper limits on how large a “small” business can be (currently $47 million in receipts or 1,500 employees).
For example, the current eligibility limit for small businesses in IT services (every code under NAICS 5415) would rise from $34–37 million to $531 million in average annual receipts, enabling much larger companies to compete for IT contracts set aside for small businesses.
By SBA’s own estimate, about 114,500 more firms would qualify as small, including 37,002 that held roughly $71 billion in FY2025 federal contracts (Federal Register). SBA extended comments to November 20, 2026, citing requests for more time (notice).
Set-aside threshold. The Trump administration has asked Congress to lighten the rules on commercial purchases up to $10 million by 2031, but to keep the legal small-business reservation at today’s $350,000 rather than let it grow with the new limit. Small businesses would keep the protection they have today, but would not share in the expansion (July 2026 legislative proposals, published by GSA).
By its own yardstick, the government is succeeding at small-business contracting. It has met its 23% small-business goal every year since FY2013, and SBA has graded it an A in each of the last five years, including FY2025, when small businesses won 27.6% of prime contract dollars, about $179 billion (SBA scorecard).
But, over the same stretch, the actual number of small businesses winning any of those dollars fell from 93,170 in FY2013 to 56,725 in FY2025, a drop of nearly 40% (SBA Small Business Data Hub; Washington Technology).
More money is flowing to fewer, larger small businesses.
If the size rule passes as drafted, set-aside competitions will fill with firms many times larger than today’s typical small business. For example, in IT services, firms with up to $531 million in revenue would count as small.
Micro and emerging firms would need to compete against them to prime or retreat to subcontracting.
As contracts held by newly “small” firms are recompeted, those dollars count toward small-business goals, so the headline percentage could keep rising while the number of genuinely small firms keeps falling.
Direction and momentum. Small businesses in contracting continue to fall steadily, with a plausible acceleration in 2027–2028.
Likely that the number of small businesses winning prime contracts, measured under today’s size standards, will be lower in FY2031 than FY2025. Plausible that a final size rule lands close to the proposal.
Plausible · 8. Vendor-count decline from SBA’s own Small Business Data Hub, corroborated by Bloomberg Government and Washington Technology; size-rule outcome rated 4 since it is only proposed.
A final size rule that keeps ceilings, or FY2026 data showing first-time small-business entrants rising.
Risk moves to the contractor
Contractors are being asked to carry more of the cost risk. Fixed price is becoming the default, so a contractor that runs over budget absorbs the extra cost instead of passing it to the government. In exchange, the government is requiring less cost data and doing less auditing. Defense contractors face an added condition: if they deliver late, they can be barred from stock buybacks and dividends, and executive pay is tied to on-time delivery.
Indicator: contract-type mix; new clauses on capital allocation.
Executive Order 14402 (April 30, 2026) makes fixed-price the default, a shift that reaches a large share of spending. For example, in FY2025, about $262 billion, roughly a third of all federal contract dollars, went through non-fixed-price contracts, the kind the order now discourages (GAO dashboard data; our calculation).
Contracting officers must justify any other contract type in writing, and agency heads must approve those above set thresholds:
- $100 million at the Department of War
- $35 million at NASA
- $25 million at DHS
- $10 million elsewhere
Each agency also had 90 days to review its 10 largest non-fixed-price contracts (EO 14402).
OMB’s implementing guidance sets two deadlines for justifying non-fixed-price contracts above the thresholds (OMB/FAR Council guidance):
- New solicitations issued on or after July 15, 2026: the justification must be approved before the solicitation goes out.
- Existing contracts with 18 or more months left: an approved justification should be in place by July 15, 2027.
The January 2026 “Prioritizing the Warfighter” order (EO 14372) goes further for defense. Future contracts must:
- bar stock buybacks and dividends during periods of underperformance
- tie executive incentive pay to on-time delivery and increased production
- let the Secretary of War cap executive base salaries after an underperformance finding (EO 14372)
At the same time, oversight paperwork is shrinking. For DoD, NASA and Coast Guard contracts entered after June 30, 2026, the threshold for certified cost or pricing data (TINA) rose from $2 million in statute (about $2.5 million after inflation adjustment) to $10 million (10 U.S.C. 3702, as amended by the FY2026 NDAA §1804). Civilian agencies were not included.
The government has pushed fixed-price contracting before, and the results depended on what was being bought. For development work, where no one yet knows what the product will cost to build, it has repeatedly gone badly (see “Fixed-price development: the track record”). EO 14402 appears to have absorbed that lesson: it exempts research and pre-production development from its agency-head approval rule. The untested part is services, where requirements are often ill-defined and the order applies in full.
Fixed-price development: the track record
- 1965C-5A transport
Bought under a single fixed-price contract covering development and production. Cost overruns and wing problems followed; the Air Force paid about $1 billion more than the original contract while cutting its order from 115 to 81 aircraft, and the Pentagon abandoned the approach. (Air Force)
- 1988A-12 attack jet
Fixed-price incentive contract, $4.8 billion ceiling. Terminated for default in 1991 after the contractors said they would overrun the ceiling by more than they could absorb; about $3 billion spent, no aircraft delivered. (GAO)
- 2011KC-46 tanker
Boeing has lost more than $8 billion on the fixed-price program; its CEO called it “a bad contract for the last decade.” (Defense News)
- 2017–2022Section 829
A general DoD preference for fixed-price, repealed in the FY2022 NDAA not because it failed, but because Congress concluded fixed-price “may not be suitable for all acquisitions.” (Senate Report 117-39; DFARS Case 2022-D007)
Bidders price uncertainty in, so ill-defined work may draw fewer bids at higher prices. Firms with weak cost estimating could win and lose money. The shift lands hardest on civilian services: time-and-materials and labor-hour contracts made up 8.5% of civilian obligations in FY2025, against under 1% at defense agencies (GAO dashboard data). Over time, balance-sheet strength becomes a competitive advantage, which favors consolidation.
Likely that fixed-price share rises through 2028. Plausible that a partial reversal arrives by 2031.
Plausible · 6. Policy is enacted and corroborated by several law-firm analyses; market effects not yet visible in data.
FY2027 data showing no shift in contract-type mix, or quiet exception approvals becoming routine.
Fewer, bigger doors
Buying is consolidating into governmentwide enterprise agreements, mega-vehicles, and long single-award contracts.
Indicator: share of spend through existing vehicles; OneGov agreements; protest access.
Enterprise deals. GSA’s OneGov deals replaced agency-by-agency software buying with about 20 governmentwide agreements, saving a reported $1.1 billion in their first year, and GSA is now looking to expand them beyond software (GSA; Nextgov).
What is OneGov?
OneGov is a GSA initiative, launched in April 2025, that negotiates technology deals once on behalf of the whole federal government instead of agency by agency. By treating the government as a single customer, GSA has struck about 20 governmentwide agreements directly with major vendors such as Microsoft, Adobe, Google, ServiceNow and OpenAI. Agencies can then sign up for the products at the negotiated price.
The discounts are steep, up to 90% on some software, but most are temporary, with set end dates. GSA sees them as a springboard to longer-term contracts, and it reports $1.1 billion in savings in the program’s first year, a figure it calculated itself. GSA is now looking at extending OneGov beyond software to other products from the same vendors.
Mega-vehicles. The Army’s $50 billion MAPS vehicle merges two existing sets of professional-services contracts into one, with up to 350 awards across five service areas and a ten-year ordering period (GAO decision B-424433.23). It has drawn 10 protests, several challenging the consolidation itself; GAO denied those, though one sustained protest forced the Army to let small-business teams bid (Washington Technology, July; September).
Long single-award contracts. Special Operations Command’s largest services contract, a $10.5 billion, 12-year logistics recompete, went to one prime, incumbent Lockheed Martin (Lockheed Martin).
Narrower protest rights. The Trump administration has also asked Congress to raise the threshold for protesting task orders under civilian agencies’ contracts at GAO from $10 million to $35 million, matching DoD, and to apply the same limit to GSA Schedule orders, which today can be protested at any value (GSA). Orders below the threshold could then be challenged at GAO only on the grounds that they exceed the contract’s scope. Protests over how a vehicle itself is competed, like those against MAPS, would not be affected.
Vehicle access becomes market access. Many vehicles add new companies rarely or never, so missing the initial competition can mean a decade outside: MAPS orders run ten years and the SOCOM logistics contract twelve. Resellers living on license margins may face compression as agencies deal directly with software makers. Subcontracting becomes the main route in for many firms, so relationships with the primes that hold these contracts become a critical asset, and primes gain bargaining power over who joins their teams and on what terms. Protests can still pry doors open, as the MAPS small-business ruling shows, but fewer orders may be open to challenge.
Likely.
Plausible · 6. Direction documented in GSA, GAO and company records; GSA’s savings figure is self-reported, and no governmentwide measure of vehicle concentration was found.
Congressional pushback on category management, or frequent open on-ramps becoming standard.
Neo-primes: the money is ahead of the market share
Venture-backed defense firms (“neo-primes”) are drawing record capital and landmark awards, but still win a small slice of total obligations.
Indicator: venture funding versus share of DoD contract dollars.
Venture money is pouring in. By PitchBook’s count, which includes dual-use companies, venture investment in defense tech hit a record $49.1 billion in 2025, up from $27.2 billion in 2024; CB Insights, using a narrower definition, counted $17.9 billion, more than double 2024 (Defense News). The first half of 2026 added another $35.6 billion, already two-thirds of 2025’s record (PitchBook data via ClearanceJobs).
Landmark awards are following. In March 2026 the Army consolidated more than 120 separate Anduril procurement actions into a single 10-year enterprise contract worth up to $20 billion (U.S. Army).
Yet market share remains small. Govini data provided to Reuters showed defense startups winning 1.3% of Pentagon contract dollars going to defense firms in the first three quarters of 2025, up from 0.6% a year earlier, while the traditional primes held steady at 92% (Reuters, via WHBL).
The paths startups use to win government work are real and growing. DoD obligations through OTAs, the flexible contracts startups favor, grew from $1.8 billion in FY2016 to over $18 billion in FY2024 (GAO-25-107546). Defense Secretary Hegseth’s November 2025 acquisition memo made commercial products “the default policy” and directed the creation of Portfolio Acquisition Executives (PAEs) (DefenseScoop). The FY2026 NDAA then wrote that role into law and eased rules for commercial products and nontraditional defense contractors (P.L. 119-60, §§1802, 1822–1826).
Hype check. Investment and headline awards are running far ahead of actual spending: record venture funding and a “$20 billion” Anduril ceiling sit against a 1.3% share of Pentagon contract dollars. That gap is the classic fad-like pattern. But the drivers underneath (statute, OTAs, budget growth for drones and munitions) are durable. Amara’s law fits (see aside): overestimated for 2027, likely underestimated for 2031.
What is Amara’s law?
“We tend to overestimate the effect of a technology in the short run and underestimate the effect in the long run.”
Usually credited to Roy Amara, a forecaster who led the Institute for the Future in Palo Alto. It describes a common pattern: early excitement about a new technology runs ahead of reality, early results disappoint, and attention fades. Meanwhile the technology keeps improving and spreading, until years later it has changed more than anyone expected. The internet is the classic case. The dot-com crash of 2000 seemed to prove the hype wrong, but two decades later the internet had reshaped nearly every industry.
For defense startups, that suggests disappointment in the near term (slow production orders, falling valuations) alongside a larger long-term role than today’s 1.3% share implies.
Likely that nontraditional share rises; possible (10–35%) that it exceeds 5% of DoD obligations by FY2031.
Plausible for growth, possible for a step change · 6. Funding records confirmed across trackers, though definitions vary widely; share data from one source, Govini.
A high-profile neo-prime program failure, or valuations resetting as the 2026 funding wave meets slower production orders.
Rules in permanent motion
Contracting rules are changing on several fronts at once, with no sign of settling.
Indicator: count of concurrent rule regimes and reversals.
The FAR overhaul is arriving piece by piece. After starting with agency-by-agency “class deviations,” the FAR Council moved to formal rulemaking with four proposed rules on June 23, 2026 and four more on September 18, together covering 36 FAR parts (Revolutionary FAR Overhaul; Federal Register).
Part 19, which applies to small businesses, has not landed as of October 2026.
Until final rules land, a contractor can hold contracts written under the original FAR, under agency deviations and, eventually, under the final FAR, all at once. Agencies are adding their own layers too: GSA proposed changes to its supplement in September and October (Federal Register).
Cyber rules are in flux as well. On July 13, 2026, the Department of War suspended CMMC Phase II, the third-party cybersecurity certification originally due November 10, 2026; Phase I self-assessments remain in place (DoD CIO). A CMMC Reform Task Force was given 60 days to review the program (Greenberg Traurig), but as of late October the CIO’s CMMC page lists no report. Even the underlying standard is split. DoD’s CMMC rules are built on NIST SP 800-171 Revision 2 (32 CFR Part 170), while the FAR overhaul’s June proposal would require Revision 3 governmentwide, using DoD’s own parameters (Federal Register).
Why we call this stable
In our framework, a “stable condition” is a state that persists rather than a trend heading somewhere. We expect this volatility to last through at least the 2028 election. The rules keep oscillating because so much rests on executive orders that a future administration can reverse as quickly as they were made.
Almost certain (above 90%) that at least one major contracting rule is reversed or substantially revised before 2031.
Plausible · 8. Primary records: Federal Register, eCFR, DoD CIO; corroborated by law-firm analysis.
Final FAR rules plus a published CMMC reform that both survive the 2028 transition intact.
AI on both sides of the table
Contractors draft with AI; agencies increasingly screen with AI.
Indicator: agency AI-evaluation pilots; proposal volumes; acquisition workforce size.
On the industry side, a federal AI adviser says AI lets companies respond to roughly ten times as many opportunities as before, and NIH’s NITAAC director says evaluators can already spot heavily AI-written proposals because many share strikingly similar language or even the same mistakes (GovCIO).
On the agency side, officials describe using AI to manage the resulting flood of proposals with an initial “administrative sweep” (for example, checking small-business status) while keeping technical evaluation with humans (GovCIO).
The Defense Intelligence Agency issued a request for information on June 17, 2026 for an AI-powered acquisition platform covering proposal intake, evaluation workflows and compliance checks (DefenseScoop).
A paper at the Naval Postgraduate School’s 2026 Acquisition Research Symposium warns of an “AI-to-AI” procurement system in which government AI reviews proposals drafted by industry AI (NPS).
Meanwhile, fewer people are doing the reading: GSA’s acquisition workforce fell 30% over the past year, according to its senior procurement executive (FedScoop).
If drafting becomes cheap, proposal volume rises, and evaluators lean harder on automated screening. Differentiation may shift from prose quality to verifiable data: past-performance records, CPARS ratings and machine-checkable compliance.
Plausible that AI screening becomes routine at major civilian buying offices by 2029.
Possible to plausible · 4. Consistent pattern across practitioner and research venues; no hard adoption data; single-source on volume.
An OMB rule restricting AI in source selection, or a protest decision that sets limits.
Alternative futures for FY2031
Through 2028 the push of the present dominates the Futures Triangle: a defense-heavy budget, executive orders, and new buying tools. The pull is a vision of faster, commercial-first acquisition. The weight of the past is statute, appropriations politics, protests, and incumbent vehicles. Because so much of today’s change rests on executive orders, the cone widens sharply after the 2028 election.
What is the Futures Triangle?
A framework from futurist Sohail Inayatullah that sorts the forces shaping a future into three groups. The push of the present is the trends and pressures driving change now. The pull of the future is the vision people are working toward. The weight of the past is the laws, habits and institutions that resist change. Where the three forces balance tells you how much room there is for the future to differ from today.
The cone stays narrow until 2028, then widens into three futures
Branching points (triangles) and alternative futures for federal contracting, FY2027 to FY2031
Momentum carries the near term; the 2028 election is the widest branching point, and a wider war is the wildcard that leaves the cone entirely.
Momentum (most likely)
Findings 1–4 run their course. Defense holds well above its FY2024 share, buying runs through a small set of enterprise deals and mega-vehicles, fixed-price is routine, and the small-business vendor count keeps falling while “small” is defined more broadly.
Pendulum (plausible)
A post-2028 administration or Congress codifies some reforms and reverses others. Civilian budgets recover, set-aside protections are restored, and cost-type contracts return for development work, echoing the 2022 reversal of the 2017 fixed-price preference.
Squeeze (possible)
Reconciliation money never materializes and debt service crowds out discretionary spending. Defense settles near OMB’s no-reconciliation path of about $1.28–1.35 trillion, civilian spending falls further, and competition for a flat pie intensifies.
Mobilization (wildcard)
An expanded war turns large parts of the market into a production economy under the Defense Production Act, with multiyear munitions buys, priority ratings, and capital-allocation controls on suppliers.
Contradictions and data gaps
- FY2025 totals differ by source. GAO reports about $793 billion; Bloomberg Government about $808 billion; GovSpend $834 billion including Other Transactions. Each uses a different scope, so this report anchors on GAO and treats the others as directional. [GAO: 8; BGov and GovSpend: 6]
- Small-business dollars disagree. Estimates for FY2025 range from $171.5 billion (BGov, down 3%) and $172.6 billion (GovSpend) to $179 billion (FNN) and a “record” $195 billion (Deltek). Sources agree on the direction of the vendor count (down) but not on dollars. The disagreement is reported, not averaged.
- CMMC capacity. Some vendors describe a long assessor backlog; others argue the real gap is contractor readiness. Both are commercially interested (confidence 2). The July pause makes this moot until the task force reports.
- Contracting workforce. A widely shared “40% fewer contracting officers” figure traces to commentary, not hard data. Only GSA’s ~30% drop is sourced here; government-wide 1102 data for 2026 was not found.
- Neo-prime share rests on one analytics source (Govini). Treat as directional.
- “DOGE shrank federal contracting.” Fad-like as a spending story: totals rose in FY2025. Its real legacy shows up in findings 1, 2 and 4 (civilian services cuts, vendor exits, consolidation).
- “AI will replace service contractors.” Too thinly evidenced for a five-year call; folded into finding 7 as a weak signal.
- Tariffs and input-cost inflation. Real for manufacturers, but evidence on contract-level effects was too thin to rank.
| Uncertainty | Type | What to track |
|---|---|---|
| Will Reconciliation 3.0 pass with ~$350B in defense money? | Fundamental (political) | Senate votes after the November 2026 midterms |
| Will the SBA size rule finalize close to the proposal? | Reducible | Final rule text after the November 20, 2026 comment deadline |
| What replaces CMMC Phase 2? | Reducible | Task-force report, expected around October 2026 |
| Do fixed-price conversions cause overruns, disputes, or no-bids? | Reducible over time | FY2027–FY2028 contract-type mix; claims and terminations |
| Do executive-order reforms survive the 2028 election? | Fundamental | Codification in NDAA or statute vs. reliance on EOs |
| How fast does the Iran war supplemental reshape munitions and production demand? | Fundamental | Supplemental enactment; multiyear procurement awards |
The counter-case
Arguing against our top three. On finding 1, a war supplemental and lower civilian spending could be temporary, and appropriators historically protect non-defense programs; we lowered the post-2028 call to “plausible.” On finding 2, the decline may partly reflect healthy cleanup of pass-through firms, and dollars per small firm are rising; the finding stands, but the reading of it as purely negative does not. On finding 3, contracting officers may simply justify exceptions routinely; that is why confidence is 6, not 8.
What we set out to answer
Which shifts in how the US government funds, buys, and pays for goods and services are most likely to reshape the contractor market from FY2027 through FY2031, and which are being underweighted?
Five years, October 2026 to September 2031 (FY2027–FY2031).
US federal market, prime and subcontract tiers.
The contractor: large primes, mid-tier integrators, small businesses, and venture-backed nontraditionals.
Defense-first budgeting and executive-order governance.
Record totals, falling civilian share, venture capital flooding defense tech.
A smaller federal workforce leaning harder on contractors and tools.
AI on both sides of the proposal.
Marginal in this horizon.
A FAR rewrite, a size-standard rewrite, and a paused cyber certification regime all in flight.
Application in this outlook:
- Political and Legal carry the most weight because statute, executive orders, and the FAR are all moving at once.
- Economic (budget mix) and Technological (AI, commercial-first buying) come next.
- Social and Environmental drivers get one line each; they matter only at the margins of this system.
Ranking logic: impact × confidence, with novelty breaking ties.
Functions, drivers, blockers
For this study we break federal contracting into seven functions. In each one, specific drivers push for change and specific blockers resist it.
Our system map shows the market from the contractor’s side. It adapts the standard contract lifecycle and DoD’s ‘Big A’ view of budgets, requirements, and acquisition. The outlook reflects our prediction of how strongly the drivers and blockers will act on each function.
Indicator: Most lifecycle models treat compliance as a thread running through every phase. We treat Comply and certify as its own function because that is how contractors experience it.
| Function | Drivers pushing change | Blockers resisting change |
|---|---|---|
| Fund | $1.5T FY2027 defense request; reconciliation money; war supplemental | Continuing resolutions; 10% proposed non-defense cut; Congress resisting reconciliation as a substitute for appropriations |
| Define requirements | Portfolio Acquisition Executives; commercial-first mandates | Legacy programs of record; requirements culture |
| Solicit and compete | FAR overhaul; higher thresholds; AI-assisted evaluation | Thinner contracting workforce; protest risk |
| Award | GSA consolidation; OneGov; mega-IDIQs; OTAs | Bid protests; competition statutes |
| Perform and deliver | Fixed-price default; buyback/dividend EO; multiyear munitions buys | Supply-chain capacity; cost risk |
| Comply and certify | 8(a) audit; size-standard overhaul; CUI rule | CMMC pause; cost of compliance for small firms |
| Pay and close out | Payment withholding on protests; TINA and CAS thresholds raised | Shutdown and CR cash-flow gaps |
How to read this report
This outlook uses methods from strategic foresight, the practice of studying how change happens so an organization can prepare for more than one future. These are the terms we use.
- PESTEL
- A checklist of six kinds of drivers of change: Political, Economic, Social, Technological, Environmental and Legal.
- Probability
- How likely an outcome is: almost certain (above 90%), likely (65–90%), plausible (35–65%) or possible (10–35%).
- Confidence (8/6/4/2)
- How well the evidence supports a finding, based on the strength of its sources:
- 8Primary records or official data (GAO, the Federal Register, SEC filings), backed by independent sources
- 6Credible secondary sources, such as established trade press or law-firm analysis, or policy that is enacted but whose effects don’t yet show in data
- 4A consistent pattern across practitioners or researchers but no hard data, or only one source
- 2Claims from sources with a commercial interest, or claims nobody else backs up
- Range
- Where a finding’s outcome sits in the cone of possibilities, the widening spread of futures shown under Alternative futures. Near-term outcomes sit in a narrow band, and the spread widens the further out we look. Probable outcomes follow today’s path, plausible ones fit what we know now, and possible ones could happen but depend on several things changing. Range describes the shape of the future; the probability figure says how likely one outcome is.
- Finding types
- A trend is a change already under way that shows up in data and has a clear direction. An emerging issue is a development that has started, often a new policy, whose effects aren’t yet visible in data. A weak signal is an early, scattered sign of a possible change, with little hard evidence yet. A stable condition is a state that persists rather than moving in one direction. A hype gap is attention and investment running well ahead of actual adoption or spending.
- Impact and ranking
- Impact is how much the contractor market would change if a finding plays out. We rank findings by impact multiplied by confidence. When two tie, the less widely recognized one ranks higher.
- Direction and momentum
- Direction is which way a finding is moving (rising, falling or oscillating). Momentum is whether that movement is speeding up, holding steady or slowing.
- Indicators and signposts
- An indicator is the measure we use to track a finding. A signpost is a specific event or data release worth watching because it would show which way the finding is heading.
- Branching points and wildcards
- A branching point is a moment, such as an election or a budget vote, where the outcome sends the future down noticeably different paths. A wildcard is a low-probability, high-impact event that falls outside the cone entirely.
- Reducible and fundamental uncertainty
- A reducible uncertainty will resolve with time or more information, such as a final rule being published. A fundamental uncertainty can’t be known ahead of time, such as how an election turns out.
- PABB (Paradigms, Assumptions, Beliefs, and Biases) check
- A deliberate counter-case: we argue against our top findings to test whether they hold up, and adjust the calls where the counter-argument is strong.
Download the full report
The complete outlook as a print-ready PDF: all seven findings, the alternative futures, the signposts to watch, and links to every primary source.
Ready to connect your pursuit work?
GovEagle gives BD directors, capture managers, and proposal teams one AI workspace from pipeline through proposal, with CMMC/FedRAMP Certified compliance built in.